
FRA Issues Landmark Decree to Regulate Hedge Funds in Egypt for the First Time
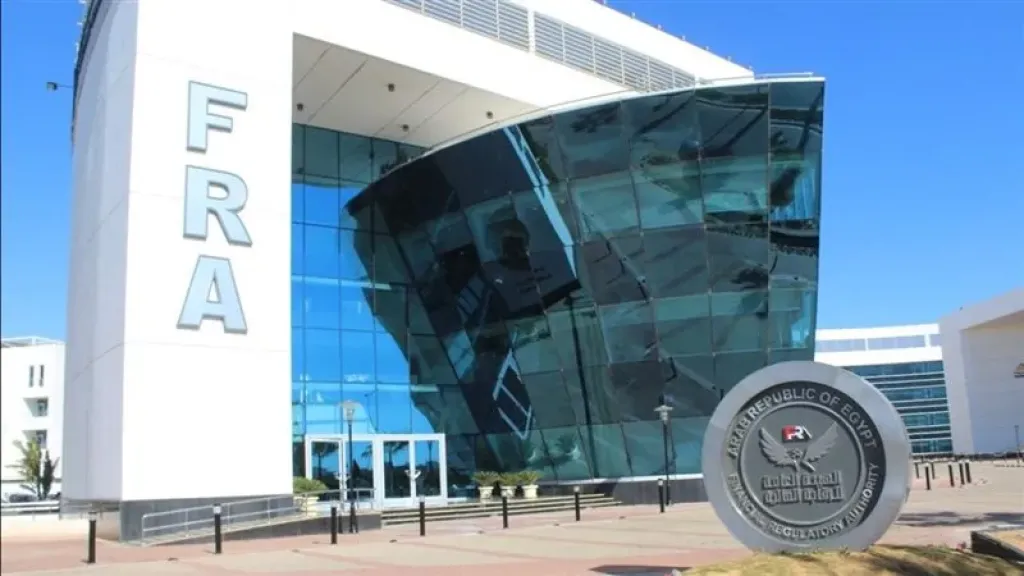
The Egyptian Official Gazette has published Decree No. (154) of 2026, issued by the Board of Directors of the Financial Regulatory Authority (FRA) chaired by Dr. Islam Azzam. The landmark decision introduces, for the first time, a comprehensive regulatory framework for establishing hedge funds in Egypt. These funds will invest in equities, debt instruments, financial derivatives—such as forward, futures, and options contracts—as well as engage in short selling and trade other highly liquid financial instruments on the Egyptian Exchange (EGX).
According to the decree, the FRA will license the establishment of hedge funds subject to the investment limits and controls outlined in the fund’s prospectus or information memorandum, following FRA approval. Furthermore, the decree permits existing mutual funds to conduct hedge fund activities under specific guidelines in accordance with the Capital Market Law No. 95 of 1992 and its executive regulations.
The licensing process allows for either the incorporation of a new hedge fund or the transition of an existing mutual fund into a 'multi-issuance fund' designed to invest in listed securities, utilizing specialized trading strategies and mechanisms approved by the Authority.
Fund management companies seeking to engage in hedge fund activities must submit board approval to amend their prospectus or information memorandum. The updated portfolio structure must consist of EGX-listed securities and instruments, open-ended or exchange-traded fund (ETF) units, listed derivatives, and any other financial instruments approved by the FRA Board.
**Prospectus and Risk Management Requirements**
The decree mandates that the prospectus or information memorandum include fundamental data stipulated by the Capital Market Law's executive regulations, along with additional critical disclosures. These include the fund’s investment policy, target investor criteria (with verification mechanisms by subscription receiving entities), and acceptable risk limits to achieve target returns.
Specifically, the risk framework must define leverage limits, counterparty exposure—particularly in securities lending, borrowing, and derivatives—liquidity limits, concentration limits, stress testing, stop-loss mechanisms, and other essential risk management controls. It must also outline the fund's performance evaluation methodology, incorporating risk-adjusted return metrics and benchmark indicators.
**Comprehensive Investment Policy**
The investment policy must thoroughly detail the target investment areas, asset allocation structure, maximum and minimum investment limits per asset class, and the specific strategies employed by the investment manager. It must clarify the objectives, risks, and usage limits of specialized trading mechanisms like derivatives, short selling, and margin trading. Additionally, it must stipulate borrowing limits, liquidity management policies, and mechanisms for fulfilling or suspending redemption requests.
The investment manager is required to possess specialized expertise in hedge fund strategies and the necessary monetary systems. Obligations include assessing counterparty creditworthiness, monitoring leverage to ensure compliance with prospectus limits, conducting regular stress tests and scenario analyses, and verifying collateral adequacy.
**Market Impact and Investor Protection**
Dr. Islam Azzam, Chairman of the FRA, emphasized that opening the door for hedge funds is a significant milestone following recent amendments to the Capital Market Law's executive regulations. This move aligns with ongoing efforts to deepen the EGX and is expected to invigorate the derivatives market by enhancing the operational and investment flexibility of funds.
Azzam noted that hedge funds are uniquely positioned to attract new segments of local and foreign investors seeking high returns through diversified strategies. This necessitates a high degree of expertise and professionalism from investment managers to navigate volatile market conditions.
He stressed that the decree strikes a crucial balance between investment diversification and the protection of unit holders. By mandating comprehensive disclosures regarding allowable leverage, potential risks—such as compounded losses, liquidity constraints, margin calls, forced liquidation, and market volatility—the FRA ensures that robust risk management procedures are transparently enforced.
related topics
 Akamai Technologies Inks $11.6 Billion Cloud Deal with Anthropic, Shares Surge 22%
 Egypt Prepares to Restart LNG Shipments from Idku in October
 Egypt’s FRA Expands Cooperation with Arab Securities Regulators on Training and Capital...
 Egypt’s Non-Banking Financial Sector Tops Weekly Stock Trading Activity
AUSTRIACARD Delivers First Jaywan Cards to Wio Bank as UAE Builds Its...
 UNDP Praises Egypt’s Digital Transformation and Digital Egypt Platform
 Egypt’s FRA Orders Consumer Finance Firms to Link Data Systems
 Raya Holding Approves Up to $60M Investment for Proposed Egyptian Data Center...
 GrowthLabs and Amenli Forge Strategic Partnership to Launch Tailored Digital Insurance for...
 Egypt’s Banking Sector Index Falls 0.84% at Thursday’s Trading Open
 Banking Sector Stocks Show Mixed Performance at Thursday’s Trading Open
 Egypt’s National AI Council Reviews 2026 Strategy