
Comprehensive Car Insurance: Coverage Types, How to Choose the Right Insurer and File a Claim
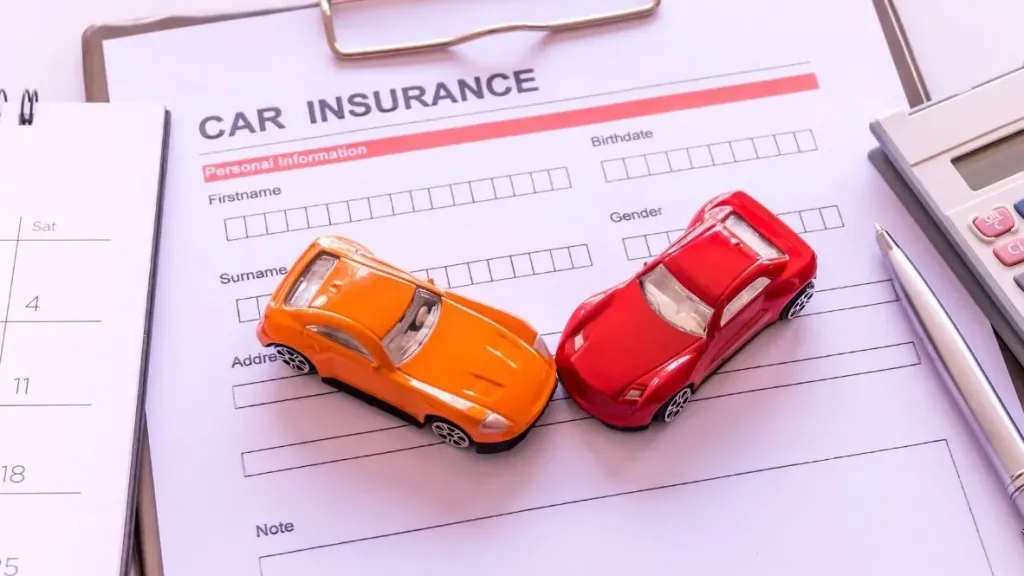
Comprehensive car insurance, generally classified in Egypt under supplementary motor insurance, offers broader protection than compulsory motor coverage. However, it does not mean that every loss or accident is automatically covered. The scope of protection and compensation varies by policy, making it essential for vehicle owners to review coverage terms and exclusions before choosing an insurer or filing a claim.
Compulsory vs. Comprehensive Coverage
Compulsory motor insurance is linked to vehicle licensing and covers civil liability within the limits established by law. Comprehensive or supplementary insurance, by contrast, is designed to protect the insured vehicle against specific risks set out in the policy. As a result, compulsory insurance does not necessarily cover the cost of repairing the policyholder's own vehicle after an accident.
Supplementary motor policies can provide different levels of protection. Coverage may include third-party property liability, fire and theft, or a broader package that typically includes collision and rollover damage alongside other agreed risks.
What Does Comprehensive Insurance Cover?
A comprehensive policy may cover collision, rollover, fire and theft, with additional services such as roadside assistance or vehicle towing depending on the insurer and policy terms. The actual compensation remains subject to the insured value, deductible, repair conditions and contractual exclusions.
The word “comprehensive” alone should not be the sole basis for comparing policies. Two policies with similar names may differ significantly in deductibles, authorised repair networks, spare-parts arrangements, additional benefits and the method used to calculate compensation in a total-loss case.
Choosing the Right Insurance Company
Drivers should compare insurers based on policy details rather than premium price alone. Key factors include the insured value, deductible, repair network, claims procedures, additional services and exclusions that could affect the policyholder's right to compensation.
The most suitable policy will depend on the vehicle's value, age and use, as well as the owner's ability to bear part of the repair cost following an accident. Customers should also verify that the insurer is licensed and keep a clear copy of the policy and its coverage schedule.
How to File a Claim
Following an accident, the policyholder should follow the procedures specified in the insurance contract and notify the insurer within the required timeframe. Required documents may include an official accident report, photographs of the damage, vehicle and driving licences, and other documents requested by the insurer.
Egypt's Financial Regulatory Authority has established rules for settling supplementary motor insurance claims. Under these rules, a vehicle should not be considered a total loss unless the approved repair cost exceeds 50% of the insured amount. If a dispute arises over the vehicle's market value at the time of the claim, the insurer must arrange for one or more additional experts to reassess the value at the company's expense.