Amr Aboul Azm: Behavioral Scoring and Data Analytics Are Reshaping Lending Decisions and Expanding Financial Inclusion
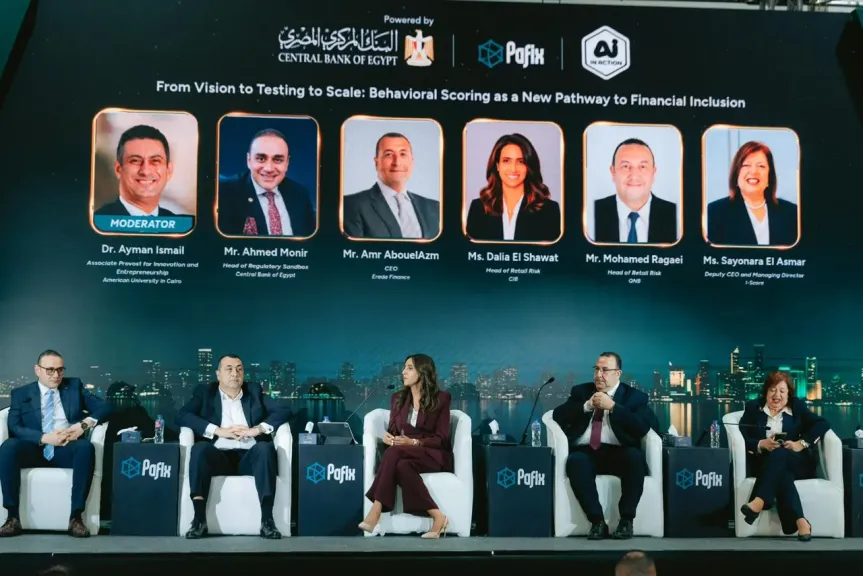
Amr Aboul Azm, CEO of Erada Finance, said behavioral scoring and integrated data analytics have become essential to improving financing decisions and advancing financial inclusion, enabling financial institutions to assess creditworthiness more accurately and reach customers who lack conventional credit histories.
He made the remarks during his participation in the session “Behavioral Scoring: New Horizons for Financial Inclusion” at Cairo ICT 2026. The session explored how behavioral assessment, technology and data analytics can improve credit decision-making, strengthen risk management and extend financial services to underserved segments. It was moderated by Dr. Ayman Ismail, Vice President for Innovation and Entrepreneurship at the American University in Cairo.
Broader data is changing credit assessment
The session brought together leaders from the financial and banking sectors to discuss developments in credit assessment tools and the importance of combining financial, social, legal and behavioral data to build a more comprehensive understanding of customers.
This approach can help financial institutions reach individuals and businesses with limited credit histories or those facing barriers to accessing financing through traditional channels.
Aboul Azm explained that creditworthiness assessments are no longer based solely on banking records or credit scores. Institutions can now draw on a wider range of indicators, including financial, social and legal information, as well as customers’ repayment behavior.
Combining these indicators provides a more accurate picture of borrowers’ credit capacity and helps institutions identify financing products that better match their needs.
Integrated information strengthens risk management
The Erada Finance CEO noted that behavioral scoring can help non-bank financial institutions improve risk management and the quality of their financing portfolios, particularly given their significant reliance on bank funding.
More comprehensive customer data can give banks clearer insight into borrower profiles and portfolio risks, supporting their assessment of financing opportunities and helping them identify the most suitable products and customer segments.
XFin supports advanced credit assessment
Aboul Azm highlighted Erada Finance’s use of technology to enhance its credit assessment framework through its XFin system, which enables integration with financing entities and supply chain finance programs.
The system also draws on specialized reports and credit alerts provided by i-Score, supporting data analysis, customer behavior monitoring and the development of more advanced credit assessment models.
He explained that this integration allows financial institutions to move beyond reliance on a single credit indicator and use multiple information sources to make more accurate and effective financing decisions.
Expanding financing solutions for SMEs
Aboul Azm added that Erada Finance has expanded its operations in recent years, moving from microfinance into financing for small and medium-sized enterprises.
The company has also diversified its offerings to include Islamic finance and supply chain finance, enabling it to serve a wider range of customers with products tailored to their business activities and credit capacity.
Behavioral scoring opens new paths to financial inclusion
He stressed that the value of behavioral assessment and data analytics goes beyond profitability and risk management, representing an opportunity to broaden financial inclusion.
Large segments of society remain outside formal banking and financing services, particularly young people and individuals who do not have bank accounts or conventional credit histories.
More flexible and accurate assessment models can help financial institutions reach these groups and provide financing products that reflect their actual needs and repayment capacity.
AI expected to accelerate instant financing decisions
Looking ahead to the next three years, Aboul Azm expects technology and artificial intelligence to play a significantly greater role in credit assessment.
He anticipates wider adoption of systems capable of instantly approving or rejecting financing applications based on comprehensive analysis of customer data.
Such systems could accelerate financing procedures, reduce reliance on paperwork and labor, lower operating expenses and decrease customer acquisition costs, ultimately helping reduce the cost of financing services.
Banks and fintech partnerships in a digital financial ecosystem
Aboul Azm also emphasized the need for banks to become more integrated into the digital financial ecosystem by strengthening partnerships with fintech companies, applications and digital platforms.
He highlighted savings and financing services aimed at lower-income groups as areas where these partnerships could have a particularly important role, adding that technology and advanced credit assessment would help extend access to a broader population.
Digital identity and data infrastructure
Concluding his remarks, Aboul Azm stressed the importance of building an integrated framework for using data and digital identity to develop a comprehensive understanding of customers beyond traditional financial information.
He said meaningful progress in financial inclusion requires continued cooperation between financial institutions and entities responsible for developing data infrastructure, helping the market reach underserved customers in the years ahead.
related topics
 ManageEngine and Saxony Egypt University Partner To Bring Industry Expertise on AI...
 Banque du Caire Reports EGP 13.1 Billion in Nine-Month 2026 Net Profit
 OpenAI Revenue Hits $10 Billion in Q3 2026, Rising 50% Quarter on...
 Satellite Internet in Egypt: How Low Earth Orbit Technology Could Transform Telecoms...
 Egypt Digital Services: A Complete Guide to Completing Government Transactions on Your...
 Laptop Buying Guide for Employees and Students: Choosing the Right Specifications for...
 Egypt’s FRA Reviews Stock Eligibility Criteria Ahead of Short Selling Launch
 Telecom Egypt Targets Level 4 Autonomous Networks Through Artificial Intelligence Adoption
 Egypt's National Telecommunication Institute Signs Two Cooperation Protocols with Obour and City...
 Egypt's ICT Ministry and UNESCO Launch Second Round of AI Training for...
 Historic Cloud Milestone: ”Telecom Egypt (WE)” Earns Two ISO Certifications and Completes...
 Banque du Caire Reports EGP 13.11 Billion in Net Profit for First...