Akef El-Maghraby: Digital Financial Identity Can Help Banks Reach 15 Million Egyptians and Reduce Customer Verification Costs
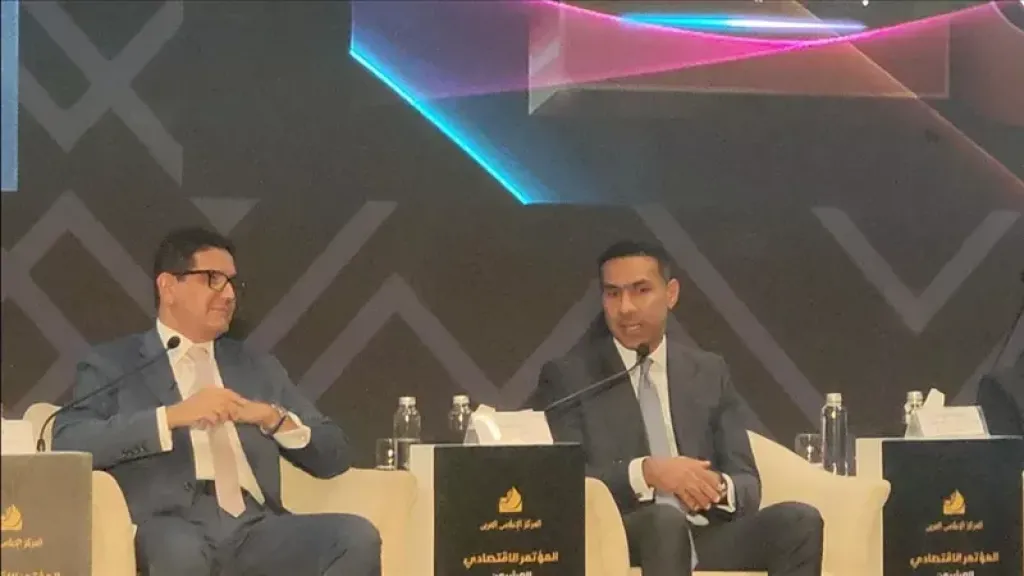
Akef El-Maghraby, CEO and Managing Director of Suez Canal Bank, highlighted the role of digital financial identity in expanding financial inclusion in Egypt by reducing customer verification costs and enabling individuals to open bank accounts and access financing and financial services remotely.
Speaking at the People and Banks Conference, El-Maghraby said Egypt's financial inclusion rate has reached 79%, representing significant progress while leaving approximately 15 million citizens outside the formal financial inclusion framework.
He explained that this remaining segment represents an important opportunity for banks to expand their customer bases through digital solutions and more efficient customer identification mechanisms.
Digital Identity Creates Opportunities for Banking Expansion
El-Maghraby noted that non-bank financial institutions serve approximately 64 million customers, reflecting the growing preference among many Egyptians for financial services offered outside the traditional banking system, largely due to easier access and simpler procedures.
He added that several non-bank financial companies have successfully expanded their customer bases through digital identity verification technologies.
According to El-Maghraby, introducing a comprehensive digital financial identity system supported by a robust cybersecurity framework would strengthen competition between banks and non-bank financial institutions while improving customer data protection.
Remote Account Opening and Lower KYC Costs
The Suez Canal Bank CEO explained that residents of villages, rural communities and areas with limited access to bank branches stand to benefit significantly from digital financial identity services.
The system would allow customers to open accounts from their homes without the time and transportation costs associated with traditional banking procedures.
He also emphasized that digital identity could reduce the expenses associated with Know Your Customer (KYC) procedures while improving services for existing customers and simplifying access to banking products.
El-Maghraby added that customers could complete identity verification once and reuse their verified information across participating banks and non-bank financial institutions, instead of repeating registration and verification procedures with each institution.
This approach would save time and effort while making it easier for customers to access services from multiple financial providers.
The system is also expected to accelerate account opening and financing procedures, helping overcome administrative obstacles that can delay access to credit.
Cybersecurity Is Essential to Digital Identity Adoption
El-Maghraby stressed that the success of digital financial identity depends on establishing a strong cybersecurity infrastructure capable of protecting customer information and maintaining trust among users and financial institutions.
He congratulated Dr. Sherif on the second edition of the Cyber Security Framework, describing it as an important component in securing the digital identity ecosystem.
He warned that concerns over data breaches and unauthorized access could discourage customers from adopting digital services and lead them to continue relying on traditional branch-based transactions.
Accordingly, strong security measures would encourage customers to share their information and use digital identities across financial institutions, while allowing banks to reduce verification expenses and extend their services to new segments.
Banking Technology Investment and Workforce Development
The Suez Canal Bank CEO also emphasized the importance of increasing investments in banking technology while providing employees with the training and skills required to keep pace with developments in Egypt's financial market.
He concluded that banks are no longer limited to delivering traditional financial products and services. Their role increasingly involves improving service delivery methods, simplifying customer access and leveraging modern technologies to enhance the overall banking experience.
related topics
 Fixed Misr FEDIS Showcases Nine Digital Solutions at Cairo ICT 2026 to...
 Cityscape Egypt Brings Together 23 Industry Leaders to Address Real Estate Market...
 National Bank of Egypt’s SME Financing Portfolio Reaches EGP 218 Billion in...
 Business and Technology Leaders at Cairo ICT 2026 Call for National Program...
 Cairo ICT 2026 Experts: Decision Intelligence Is Shaping the Next Generation of...
 Digital Transformation and Investment Expansion: Launch of the 20th ”People and Banks”...
 ”Cairo ICT 2026”: Central Bank of Egypt Launches the Second Edition of...
 ”PAFIX 2026”: Artificial Intelligence Shapes the Future of Payments and Banking Services
 ”2035 Enterprises”: AI Shapes the Future of Companies at Cairo ICT 2026
 Drive Finance Successfully Completes EGP 1.5 Billion Bond Issuance to Support Growth...
 Egypt Presents Its Digital Vision, Renews ITU Council Candidacy, and Intensifies Bilateral...
 Launch of the 5th Cohort of ”Creativa Incubation Program” with 10.8 Million...