
Egypt’s FRA Mandates Behavioral Credit Scoring Using Alternative Data for Consumer Finance Companies
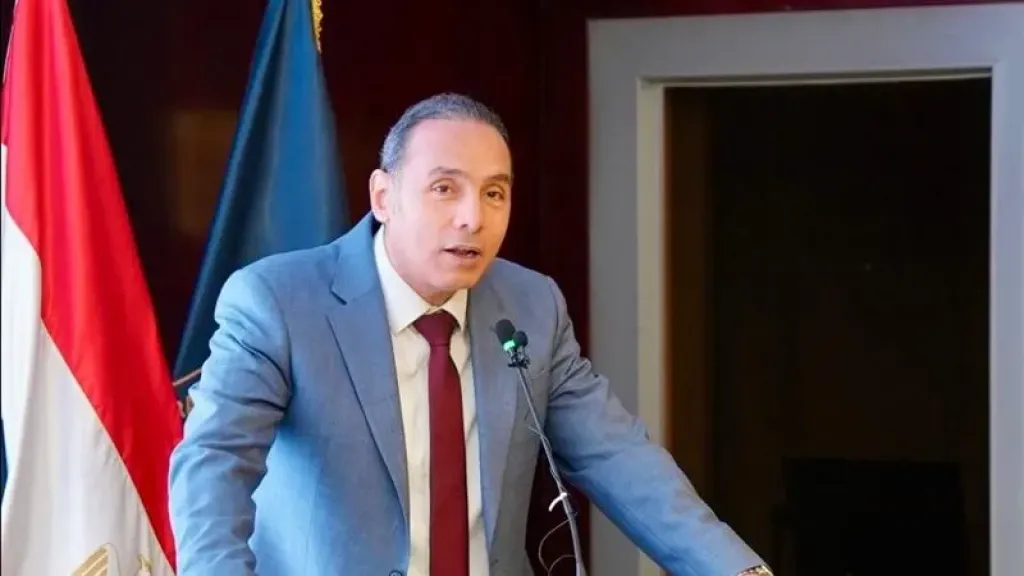
Dr. Islam Azzam, Chairman of the Financial Regulatory Authority (FRA), has issued a new directive requiring licensed consumer finance companies to incorporate behavioral credit scoring based on alternative data when evaluating clients. The mandate, formalized under Decree No. 2863 of 2026, aims to enhance credit decision-making by utilizing analytics provided by the Egyptian Credit Bureau (I-Score).
Key Regulatory Mandates
The new directive strengthens existing credit underwriting frameworks by introducing advanced digital evaluation tools:
Behavioral Scoring & Alternative Data: Companies must now factor in behavioral analytics—derived from non-traditional or alternative data sources—when approving or declining consumer finance applications.
Digital Verification Requirement: The decree mandates the strict digital verification of applicant data, building upon earlier digital identity guidelines (Decrees No. 140/2023 and 186/2024).
Implementation Timeline: Consumer finance providers are required to begin querying these new behavioral scores starting April 1, 2027, allowing time for I-Score to finalize and launch the dedicated scoring system.
These requirements supplement existing obligations under the Consumer Finance Law (No. 18 of 2020), which already mandates querying a client's historical credit exposure across both banking and non-banking financial sectors.
Strategic Objectives and Market Stability
Dr. Azzam emphasized that integrating behavioral scoring and digital verification will significantly elevate the efficiency of assessing a borrower's true creditworthiness. By gaining deeper insights into consumer financial behavior, lenders can better ensure the integrity of the credit-granting process and tangibly reduce default probabilities.
The decree is the culmination of extensive consultative meetings between the FRA, consumer finance companies, and I-Score. The regulatory objective is to strike a sustainable balance between encouraging sector growth and mitigating the operational risks of rising client defaults, which directly threaten the financial stability of lending institutions.
Dr. Azzam added that this move—alongside previous directives enforcing real-time data linking with I-Score and the accelerated adoption of OTP-based identity verification—represents a clear, continuous path toward modernizing the regulatory framework for non-banking financial services to keep pace with rapid market and technological shifts.
related topics
 iExperts Completes Four SOC 2 Projects with «e&» for Second Year
 PayPal Claims Top Spot in Roundtable 100 Tech Power Rankings Driven by...
 Global 5G Subscriptions Projected to Reach 6.4 Billion by 2031, Driven by...
 Binance Bahrain Expands Local-Currency Account Funding Options
 PayPal Tops Roundtable 100 on Stronger Earnings Outlook
 Binance Bahrain Introduces Zero-Fee Local Currency Funding and Bank Transfers to Drive...
 Space42 and Viasat to Co-Found $1B 'Equatiss' Joint Venture for Direct-to-Device Satellite...
 UAE’s InfraX and Huawei Deepen Strategic AI and Digital Infrastructure Ties During...
 17th Middle East Banking Innovation Summit (MEBIS 2026) Convenes in Dubai to...
 NTI and Huawei Expand Egypt’s ICT Talent Bank After Training More Than...
 Crude Oil Surges as Attacks on Saudi Energy Infrastructure Take East-West Pipeline...
 US Dollar Nears Two-Week High on Surging Oil Prices, Yield Spikes, and...