
Egypt’s FRA Mandates Behavioral Scoring Using Alternative Data for Consumer Finance
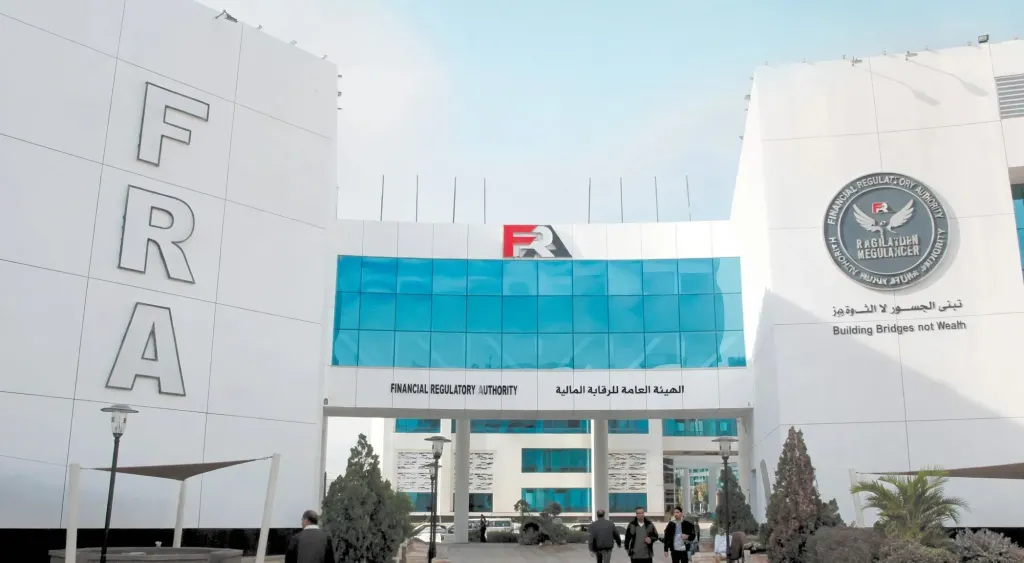
The Financial Regulatory Authority (FRA) has mandated that licensed consumer finance companies obtain customers’ behavioral credit scores based on alternative data through the Egyptian Credit Bureau (iScore).
Under the decision issued by Dr. Islam Ezzam, Chairman of the FRA, consumer finance companies will be required to digitally verify the information of customers applying for financing and access their behavioral scoring based on alternative data provided by iScore.
The new requirement will take effect on April 1, 2027, following the completion and readiness of the dedicated system at the credit bureau.
Dr. Islam Ezzam said that digital verification of customer data and access to behavioral scoring based on alternative data would improve the efficiency of creditworthiness assessment, support safer lending practices, and reduce the risk of payment defaults.
Mohamed El-Feki, a financial services expert, said the decision comes amid the rapid expansion of Egypt’s consumer finance market over the past three years. He noted that mandatory credit inquiries through iScore have contributed to the development of extensive customer databases covering individual transactions across consumer finance companies, project finance providers, and banks.
El-Feki explained that the new framework would allow companies to use these data as an integrated customer profile when making financing decisions. This could provide insights into factors such as the number of rejected applications submitted by a customer and the frequency of financing requests.
He added that the decision complements previous regulatory measures and represents a further development of Egypt’s consumer finance regulatory framework. According to El-Feki, behavioral analysis can give companies a broader view of customers’ credit behavior, payment patterns, and repayment commitments, while also providing insights into approval and rejection rates.
He also expected the use of similar mechanisms to expand into areas such as electronic purchases and digital services.