Central Bank of Egypt: AI and Alternative Data Are Essential Pillars for Credit Scoring Development and Financial Inclusion
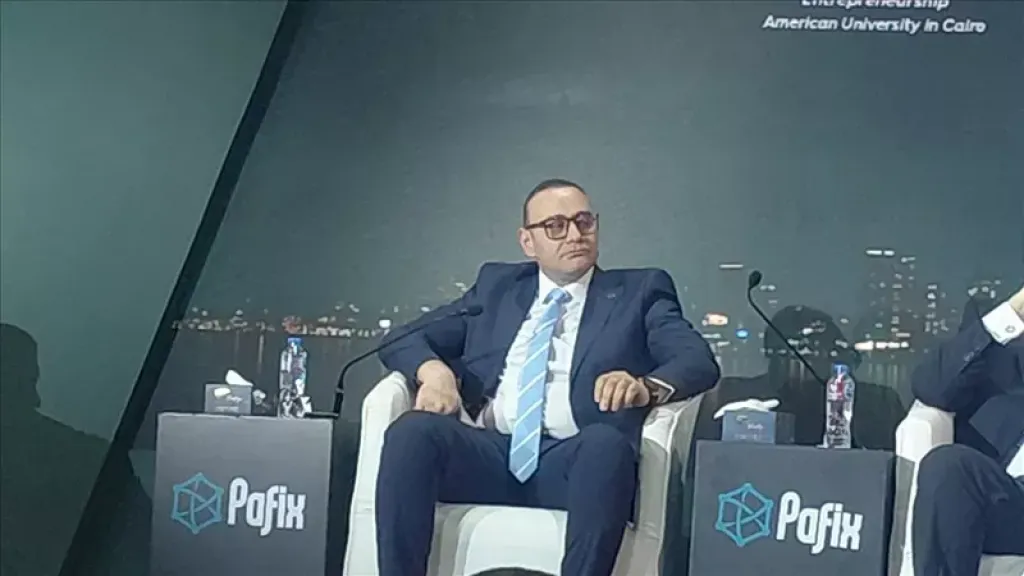
Ahmed Mounir, Head of the Regulatory Sandbox at the Central Bank of Egypt (CBE), stated that relying on alternative data and behavioral analysis represents a strategic path for updating credit scoring systems. He explained that this approach aligns with the CBE’s vision to adopt modern financial technologies—led by artificial intelligence—to expand financial inclusion and modernize banking services, supporting innovation and meeting customer needs efficiently.
Supporting Innovation and Expanding the Beneficiary Base
Mounir emphasized that behavioral scoring based on alternative data empowers financial institutions to enhance their services and offer innovative products. The significance of these technologies lies in their ability to integrate groups that lack a traditional credit history or face financing obstacles due to insufficient historical transaction data.
The Role of the Regulatory Sandbox and Regulatory Framework
The Head of the Regulatory Sandbox noted that the sandbox's role is not limited to providing an experimental environment for testing smart financial solutions. It extends to establishing a comprehensive regulatory framework to evaluate these applications, analyze associated risks, and measure their readiness for actual deployment in the banking market.
Mechanics of Behavioral Scoring and Distinguishing Capability from Willingness
Mounir pointed out that alternative data provides a comprehensive and accurate picture of a customer's financial behavior by tracking recurring payment patterns, such as utility bill payments. He highlighted the importance of separating two fundamental concepts: "financial capability to pay" and "willingness and commitment to pay," as behavioral analysis helps measure a customer's eagerness to honor commitments even without a prior bank history.
Gradual Testing and Ensuring Financial Stability
He stressed the necessity of not generalizing credit scoring model results without conducting field tests on diverse customer segments to monitor repayment and default rates and measure prediction accuracy. Mounir concluded by affirming that the true success of these technologies depends on striking a delicate balance between expanding financial inclusion and maintaining credit portfolio quality and risk management.
related topics
 ESLSCA University Launches 4th Executive Education Summit in New Cairo with Top...
 CIB Looks Toward the Future of Digital Banking and AI at Cairo...
 Strategic Partnership Between Mastercard and Housing and Development Bank to Enhance Digital...
 Osama Kamal at PAFIX Opening: Financial Inclusion in Egypt Has Become a...
 Ericsson and Vodafone Egypt to boost 5G radio network performance with AI-native...
 Cairo ICT 2026: AIDC² Conference Outlines AI and Data Center Roadmap Across...
 Egyptian Pound Sees Stable Dollar Rates as Most Banks Quote Below EGP...
 Strategic Partnership Between Telecom Egypt and e-finance to Drive Digital Transformation and...
 Egypt Launches First Digital Virtual Exhibition Platform and Digital Twin Solutions in...
 AI and Customer Awareness: National Bank of Egypt Outlines Strategy to Counter...
 Egypt’s Investment Minister Unveils AI-Powered Trade Regulatory Sandbox at Cairo ICT 2026
 Madbouly Praises National ”X-GEN” AI and Robotics Solutions at Cairo ICT 2026