
Samih Sawiris: Egypt’s Property Market Needs a Correction — and Not Every Developer Will Survive
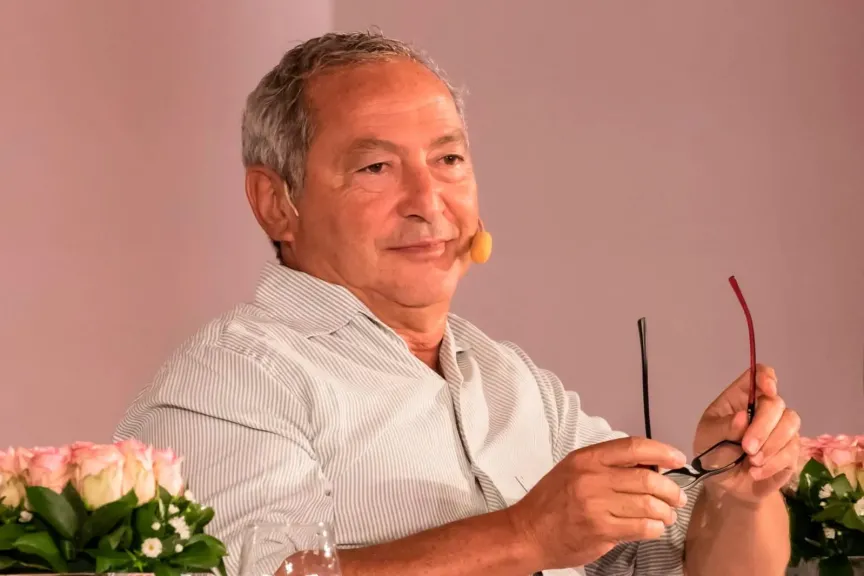
Egypt’s real estate market is approaching a period of correction that could force financially weaker developers out while leaving experienced, well-capitalized companies in a stronger position, according to businessman Samih Sawiris.
Sawiris argues that the financial difficulties facing some developers should not be interpreted as evidence of an industry-wide collapse. Instead, he sees them as part of a market reset after years in which companies with widely different levels of experience, capital and financial discipline entered the sector.
His comments come as Egypt’s property market faces growing scrutiny over project delivery, developer financing and buyers’ ability to maintain long-term installment payments, despite continued strong sales among the country’s largest developers.
Not Every Developer Needs to Survive
Speaking to television host Lamis El Hadidi on the sidelines of the opening of the ninth El Gouna Film Festival, Sawiris said some companies entered the property market without sufficient experience or capital, while others accumulated significant debt and subsequently struggled to complete projects and meet delivery commitments.
For him, the departure of such companies would not necessarily represent a failure of the wider market.
Instead, it could form part of a correction that separates developers capable of financing, building and delivering projects from businesses that depend excessively on borrowing or continuous new sales to sustain operations.
Sawiris expects established developers with a track record of construction, delivery and quality to remain, describing the eventual exit of weaker operators as a necessary part of restoring balance to the market.
That distinction is becoming increasingly important in Egypt.
After years in which land acquisitions, new launches and headline sales figures dominated the property conversation, financial resilience and actual construction progress are becoming more important measures of developer strength.
Can a Developer Survive Two Years Without Profit?
Sawiris also set a demanding benchmark for what he considers a financially sound property company.
A professionally managed developer, he argued, should be capable of surviving one or even two years without generating profits.
Temporary losses do not necessarily signal a failing business. The more important question is whether the company has sufficient financial capacity to continue construction, meet obligations and navigate difficult market conditions without threatening project delivery.
That shifts attention from reported sales to something more fundamental: liquidity.
Egypt’s property model relies heavily on off-plan sales and installment plans that can extend for several years. Contracted sales therefore do not translate immediately into equivalent cash inflows, making collections, construction costs and the timing of expenditure critical to a developer’s financial position.
Companies that rely heavily on fresh sales to finance existing commitments could consequently face greater pressure during a slowdown than developers with stronger balance sheets and more disciplined project financing.
Egypt’s Housing Demand Changes the Equation
Despite expecting some developers to leave the market, Sawiris does not believe Egypt is heading toward a broad property bubble.
His argument rests largely on demographics and the country’s underlying housing requirements.
Sawiris estimates that Egypt needs at least 500,000 new housing units every year. On that basis, he argues that stopping construction for four years could create a shortage of around two million units.
That structural demand, in his view, distinguishes Egypt from markets with stagnant populations where excess property supply can take many years to absorb.
It also creates an important distinction between two questions that are sometimes treated as one: whether Egypt needs more housing, and whether every developer currently operating in the market has a sustainable business model.
The answer to the first can remain positive even while some companies struggle with the second.
Strong Sales Do Not Remove the Risks
Other indicators underline the unusual position of the Egyptian property market.
The country’s largest developers continue to report significant contracted sales, and estimates published during 2026 have put combined sales among the top ten developers at hundreds of billions of Egyptian pounds.
At the same time, a large pipeline of units remains under development, while buyers have become increasingly selective about developers, construction progress, pricing and payment terms.
That creates a market in which strong headline demand can coexist with financial pressure at individual companies.
The key question is therefore becoming less about whether Egyptians are still buying property and more about which developers can convert sales contracts into completed projects while maintaining sufficient liquidity throughout increasingly long development and payment cycles.
Confidence Could Become the Bigger Threat
Sawiris sees another risk that extends beyond individual corporate balance sheets: confidence.
If news of developer difficulties causes buyers and sellers to become broadly concerned about the market, transactions could slow even when the fundamental need for housing remains intact.
Potential buyers may postpone purchases while waiting for greater clarity. Existing owners may hesitate to sell. Investors may become more selective about projects and developers.
The result could be a temporary freeze in market activity driven not by the disappearance of housing demand, but by uncertainty.
Sawiris believes such disruption would eventually pass, but it highlights how problems affecting a relatively small number of developers can influence sentiment across a much larger industry.
Egypt’s Next Property Cycle May Be About Delivery, Not Sales
The correction Sawiris describes could ultimately change the criteria investors and buyers use to evaluate property companies.
Land banks, ambitious launches and long installment plans helped define the previous expansion phase. The next phase could put greater weight on cash reserves, debt exposure, construction progress, delivery records and the ability to withstand periods of weaker sales.
That would also change the competitive advantage of larger developers.
Scale alone would not be enough. What matters would be whether that scale is supported by sufficient capital and operational discipline to continue building when market conditions become more difficult.
Sawiris’ assessment is therefore not that every developer will emerge safely from the current pressures.
It is that Egypt’s property market can remain fundamentally resilient even if some developers do not.
If that correction unfolds, the next chapter of Egypt’s real estate market may be defined less by how much developers can sell — and much more by how reliably they can finance, build and deliver.