
Financial Inclusion is a Core Driver of Economic Growth, Says Yasmine El-Gebaly at Connected Banking Summit
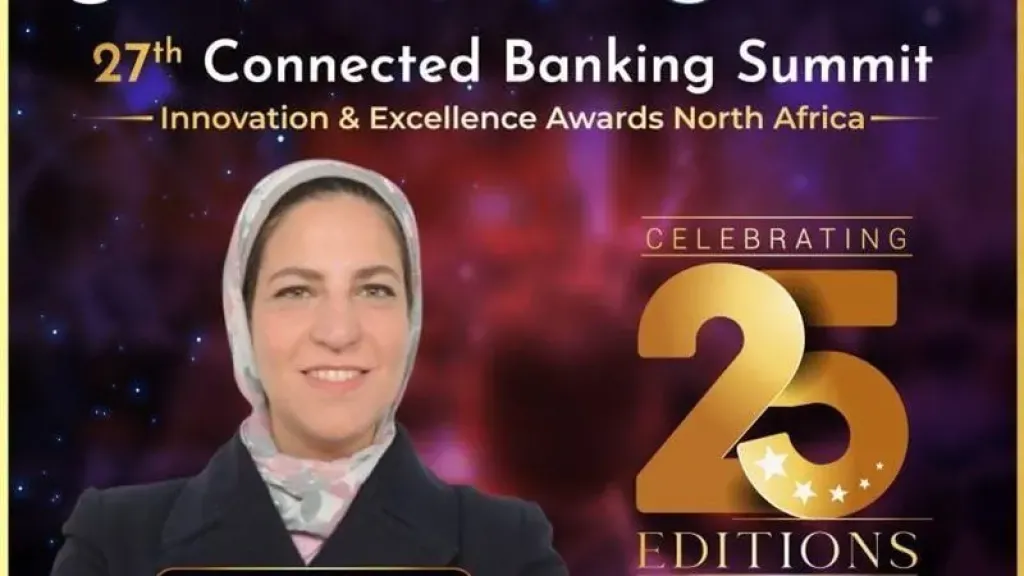
Yasmine El-Gebaly, Head of Internal Audit at the Industrial Development Bank (IDB) and Global Board Member of the Institute of Management Accountants (IMA), asserted that financial inclusion is no longer merely a concept tied to basic banking services or account access. Rather, it has evolved into a fundamental pillar for driving macroeconomic growth and empowering individuals and SMEs to actively participate in the economy.
Speaking today at the 27th Connected Banking North Africa 2026 Summit in Cairo, El-Gebaly highlighted that while fintech and innovation have dominated recent financial discourse, financial inclusion warrants special attention due to its direct impact on resource management. She noted that the evolution of this concept has rapidly accelerated since 2014, prompting banks to establish dedicated financial inclusion units.
The Macroeconomic Impact:
The core question, El-Gebaly explained, extends beyond simply providing products; it is about the broader macroeconomic impact. Economic performance is inextricably linked to citizens' ability to manage their finances and access necessary funding. Effective financial management by individuals directly translates to broader economic resilience, whereas the inability of certain segments to access suitable services hinders the economy from reaching its full potential.
Empowering SMEs Through Fintech:
El-Gebaly pointed out that technological advancements have revolutionized how small enterprises and entrepreneurs reach customers, suppliers, and global markets. Technology has given visibility to previously marginalized businesses, placing a crucial responsibility on the banking system to provide the tools necessary to foster their growth. 'As individuals and businesses evolve, so does the entire economic landscape,' she stated.
Egypt's Financial Inclusion Metrics:
Discussing Egypt's progress, she noted a significant developmental phase that began in 2018. By June 2026, the financial inclusion rate reached 79%. She added that while a segment of the population still requires further inclusion services, active financial transaction users have reached 56.4%, and women's financial inclusion has surged to 70.5%—reflecting massive progress in a short timeframe.
The Future of Traditional Banking:
Channels for financial inclusion have expanded vastly beyond traditional branches, now encompassing mobile banking, e-wallets, digital identity, online payments, and POS systems. This shift has fundamentally changed bank-client dynamics.
The traditional model of customers visiting branches during specific working hours is fading. Instead, financial institutions are now required to proactively reach users wherever they are, offering flexible, borderless digital services.
This technological evolution, El-Gebaly concluded, raises broader questions about the future of traditional banking. The shift from a branch-centric model to a customer-centric digital approach marks a profound transformation in the industry, yet banks remain indispensable in supporting individuals and SMEs and integrating them deeper into the formal economy.