
FROM MARKET REGULATION TO SHAPING THE FUTURE
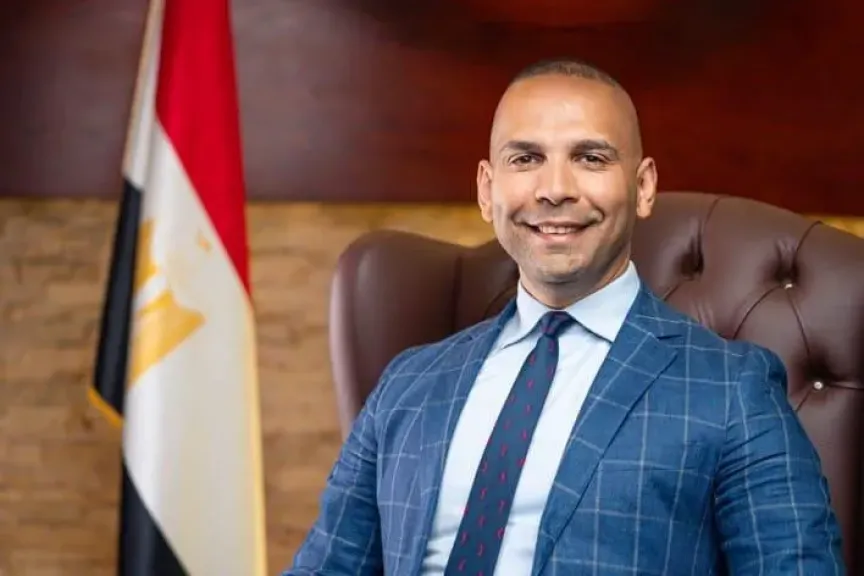
Counselor Ahmed El Adly Presents a New Vision for the Role of Legislation
in the Economy
Former Legal Counsel to the Government of the United Arab Emirates
Chairman and Founder – Al Adly & Partners:
“We do not need to replicate successful experiences; we need to understand why they succeeded
and adapt them to Egypt’s needs.”
“Legislative quality has become a competitive advantage for states, and investors seek certainty
before returns.”
“A state that provides investors with legal certainty possesses a genuine competitive advantage.”
“Law is not a constraint on investment; it is one of the most important tools for generating growth.”
“Good legislation does not merely regulate today’s economy; it helps create tomorrow’s markets.”
In a comprehensive interview on legislation, investment, decision-making, and the future of Arab
economies, Counselor Ahmed El Adly, former Legal Counsel to the Government of the United
Arab Emirates and Founder and Chairman of Al Adly & Partners, presents a vision that goes
beyond the traditional view of law as a regulatory tool and places it at the heart of the equation
for growth, investment attraction, and the creation of new markets.
In economies competing for capital and investment, legislation is no longer merely a neutral
framework; it has become one of the determinants of a country’s competitiveness. Clarity and
stability of rules, speed of procedures, institutional efficiency, and effective mechanisms for
protecting rights and resolving disputes have all become factors that directly enter an investor’s
calculations before a decision is made.
Against this backdrop, Counselor Ahmed El Adly discusses the relationship between law and
economics, drawing on practical experience working close to government decision-making circles
in the UAE. He offers a perspective on how Egypt can develop its legislative environment,
enhance its attractiveness to investment, and strike a balance between protecting the market and
supporting serious investors, while also addressing the future of legislation amid accelerating
technological and economic transformations.
LEGISLATION AND INVESTMENT
Q: Is law merely a framework for regulating the economy, or can it serve as a driver of
growth and investment?
A: In modern economies, law should not be viewed merely as a set of rules that place limits on
economic activity. Rather, it should be regarded as one of the tools for shaping markets and
directing growth.
Investors do not seek only opportunities offering high returns. They also seek an environment in
which they can anticipate their rights and obligations, understand how their investments will be
protected, know how disputes will be resolved, and determine which rules will apply to them today
and tomorrow.
Good legislation, therefore, does not merely prevent risks; it reduces the cost of uncertainty, and
that in itself represents significant economic and investment value.
Q: What constitutes successful law, and where should the institutional objective lie?
A: I believe the institutional objective should shift from the concept of “regulating activity” to
“designing the investment environment.” In other words, legislation should be drafted alongside a
proper understanding of the needs of the economy, finance, technology, and capital flows.
Ultimately, successful law is law that enables an investor to say: I know the rules, I understand
the risks, and I can make a decision.
LAW BEFORE RETURNS
Q: How do laws and regulations influence investors’ decisions?
A: Investors do not read the law in isolation from the economy; they view it as part of the riskreturn equation.
Before committing capital, an investor wants to know: Are the rules clear? Are they predictable?
Are the procedures stable? Can rights be protected and enforced? And how will future disputes
or regulatory changes be handled?
The greater the degree of clarity and stability, the lower the cost of legal risk, and the more willing
investors become to make decisions, whether in terms of the size of the investment, its duration,
or their ability to expand.
For this reason, I do not believe that attracting investment should depend solely on incentives and
exemptions. In many cases, legislative clarity, regulatory stability, and procedural efficiency may
have a greater impact than any financial incentive.
This is why I believe the quality of the legislative environment has become a competitive
advantage for states. A state that provides investors with clear rules, effective institutions, and
reliable mechanisms for protecting rights and resolving disputes does not merely attract
investment; it also helps retain and expand it.
LEGISLATION AS A TOOL FOR GROWTH
Q: Can legislation serve as a tool for growth rather than merely as an instrument of
oversight?
A: Absolutely. In fact, I believe this is the more advanced function of legislation in the modern
economy. Traditional legislation often approached the market by asking: What should we prohibit?
What should we monitor? Modern economic legislation should ask different questions: How do
we create a more efficient market? How do we open the way for investment, innovation, and
competition while preserving the protection of rights?
Legislation can create entirely new markets when it provides legal recognition for new economic
instruments and models and establishes clear rules for operating within them. In my view, the true
measure of any economic legislation is not the number of restrictions it imposes, but the value it
adds to the economy compared with the regulatory cost it creates.
We need legislation that protects without suffocating, regulates without obstructing, and opens
the door to innovation without ignoring risks. Most importantly, legislation should not be the end
of the dialogue; it should be the beginning of a continuous cycle of implementation, impact
assessment, review, and development.
If we want a more competitive economy, we must treat legislation as part of the state’s economic
infrastructure, just as we treat roads, energy, and telecommunications.
Good law does not merely regulate the market that exists today; it helps build the market we want
to exist tomorrow.
AT THE HEART OF DECISION-MAKING
Q: What did your government experience teach you about the relationship between
legislation and decision-making?
A: The most important lesson I learned from working close to government decision-making is that
legislation is not made in a vacuum, and it should neither begin nor end with the legal text itself.
Good legislation begins with understanding the economic or social problem, then studying
alternatives, listening to stakeholders, assessing the expected impact, and only then drafting an
enforceable legal rule. It also requires applying the concept of public participation before a law is
issued. There is a significant difference between legislation that is legally sound and legislation
that is successful in practice.
From experience, I believe effective legislative decision-making requires three fundamental
elements: a clear vision, accurate information, and a continuous mechanism for measuring impact
after implementation. There is also a principal condition: the law must actually be enforced
through comprehensive legal governance, alongside the availability of genuinely qualified
professionals not merely employees who have spent enough time within the government system
to be considered eligible to assume such roles. That is where the key lies.
Success does not lie merely in issuing a law, but in determining whether it achieved the objective
for which it was enacted, whether it created unintended consequences, and whether it needs
further development. This is the concept of “dynamic legislation”: legislation that keeps pace with
the economy rather than waiting until reality has moved years ahead of it.
EGYPT AND THE UAE
Q: What can Arab markets learn from the UAE’s experience in developing the business
environment?
A: I believe the most important lesson is not a particular law, but rather the methodology used to
build the legislative and investment environment.
The UAE recognized early on that attracting investment does not depend solely on incentives. It
requires an integrated ecosystem comprising clear legislation, effective regulatory authorities,
efficient procedures, a reliable judicial and arbitration framework, and clear protection of rights.
However, I do not believe in transferring one country’s experience to another literally. What can
be transferred are the reasons for success, which can then be redesigned to suit the particular
characteristics of each market.
Egypt has a vast market, a broad investor base, and enormous economic potential. The real
challenge, in my view, is to transform these strengths into a legislative and institutional competitive
advantage by reducing unnecessary procedures, unifying the regulatory vision, increasing
predictability of the rules, and linking legislation to development and investment objectives.
The goal is not for Arab markets to become identical, but for them to become more efficient, more
competitive, and better able to attract capital.
THE PROFESSIONAL INVESTOR
Q: How does a professional investor assess legal risks before committing capital?
A: A professional investor does not ask only, “How much will I earn?” Before that, the investor
asks, “What could prevent me from achieving that return?” This is why legal risk assessment has
become an essential component of economic feasibility studies.
Investors examine several levels: ownership of assets, licenses, contracts, regulatory obligations,
taxation, financing, partners’ rights, exit mechanisms, intellectual property protection, and finally,
dispute-resolution mechanisms.
What matters most, however, is not the mere existence of risks, but whether they can be
anticipated, assessed, and managed. There is no investment environment without risk, nor should
eliminating all risk be the objective. The objective is for risks to be clear, assessable, and
manageable.
This is why modern legal advice has become part of the investment decision-making process
rather than merely a review of contracts after the decision has already been made.
REAL ESTATE AND LEGISLATION
Q: How can legislation strike a balance between protecting investors and regulating the
market?
A: The real estate market in particular requires this balance, because excessive regulation can
slow the market, while insufficient regulation can undermine confidence and increase risk.
In my view, the solution is not to increase restrictions, but to establish clear rules that protect
funds while leaving serious developers sufficient room to innovate and grow. Among the areas
that deserve continuous development are the regulation of off-plan sales, protection of
purchasers’ funds, project escrow accounts, disclosure, contract registration, and mechanisms
for dealing with stalled or distressed projects.
The objective should be to build a system in which project funds are tied to the project, disclosure
is tied to accountability, and expenditure is linked to actual progress in implementation. Egypt can
benefit from successful regional experiences, including that of the UAE, but only after examining
how they can be adapted to Egypt’s legal and economic system.
I believe the correct equation is: purchaser protection + support for serious developers + market
stability.
If that equation is achieved, legislation becomes a tool for growth rather than an obstacle to it.
A NEW INDUSTRIAL LAW
Q: Egypt is seeking to strengthen domestic production, increase exports, attract
industrial investment, and localize technology and supply chains. In your view, why do
challenges remain despite the availability of financing, land, and incentives?
A: There is no doubt that achieving these objectives depends not only on the availability of
financing, land, or incentives, but also on the existence of a clear, stable, and predictable
legislative and regulatory environment.
Industrial investment is inherently long-term. An investor therefore needs to understand not only
the conditions for entering the market, but also the rules that will govern the entire life cycle of the
project, from establishment through production, expansion, and export.
Q: Is the problem the multiplicity of laws or the multiplicity of procedures?
A: It may be a mistake to reduce the problem simply to the number of laws.
Numerous laws can operate efficiently if responsibilities are clear and procedures are
interconnected. Conversely, multiple procedures, authorities, or overlapping requirements can
raise compliance costs even when the legislation itself is well drafted.
The more important question, therefore, is not: How many laws are there? Rather, it is: Do these
laws operate as a single coherent system?
Q: Does Egypt need a new industrial law that consolidates the legislative framework
governing industry?
A: In my assessment, this deserves careful institutional study, but the answer is not necessarily
to issue a new comprehensive law.
A more effective option may be to develop an integrated industrial legislative framework that
reorganizes the relationship among laws, authorities, and procedures and clearly defines the life
cycle of an industrial project from establishment through production and export.
Such a framework could be based on several principles: clarity of jurisdiction, simplification of
procedures, digitalization, stability of rules, prompt grievance mechanisms, investment protection,
and enhanced export competitiveness.
The true value of any industrial law will not be measured by the number of its provisions, but by
its ability to reduce uncertainty, lower compliance costs, and improve the competitiveness of
Egyptian industry.
INDUSTRY AND EXPORTS
Q: How can the link between industry and exports be restored?
A: If Egypt aims to increase exports, the legal framework governing industry should not view a
factory merely as an establishment producing for the domestic market.
An exporting manufacturer needs an environment that enables it to import production inputs
efficiently, comply with specifications and standards, protect intellectual property rights, enter into
international contracts, navigate international trade rules, and resolve cross-border commercial
disputes.
Against this background, the competitiveness of Egyptian industry begins, in part, with the quality
of the legal framework within which it operates.
TECHNOLOGY MOVES FASTER THAN LEGISLATION
Q: Does innovation move faster than legislation? And how should the region deal with
artificial intelligence, digital assets, and financial technology?
A: In many cases, yes. Technology moves faster than legislation, and this is not merely an Arab
problem; it is a global challenge.
The problem begins when we attempt to regulate a new technology using legal tools designed for
a different era.
I therefore believe we need to move from reactive legislation to proactive legislation meaning that
we begin studying risks and opportunities before a phenomenon becomes widespread.
In areas such as artificial intelligence, digital assets, and financial technology, the question should
not be, “How do we prevent the technology?” Rather, it should be, “How do we enable innovation
while protecting the market, users, and investors?” Important solutions include providing flexible
regulatory spaces, such as regulatory sandboxes, alongside clear rules governing liability, data
protection, fraud prevention, transparency, and risk management.
The objective is not for legislation always to move ahead of technology that would be unrealistic
but for the response time of legislative and regulatory institutions to remain reasonably close to
the pace of technological development.
ARBITRATION AND DISPUTE MANAGEMENT
Q: Why has dispute management become part of investment strategy rather than merely
a stage that follows the occurrence of a problem?
A: Because a professional investor does not wait for a dispute to arise before thinking about how
it should be managed.
In the modern economy, potential disputes should be considered when structuring a transaction
from the outset: Which law will apply? Which forum will have jurisdiction? Would arbitration be
appropriate? How will judgments or arbitral awards be enforced? And what mechanism will
provide the fastest and most efficient protection for the investment?
This represents a shift from the concept of “dispute resolution” to “dispute-risk management.”
A good contract is not merely one that defines the parties’ rights and obligations; it also sets out
a clear scenario for what will happen if matters do not proceed as planned. Markets that provide
fast, reliable, and efficient dispute-resolution mechanisms are more attractive to investment
because capital seeks not only returns, but also legal security and the prompt recovery of rights
when necessary.
DIGITAL TRANSFORMATION
Q: How can digital transformation contribute to industrial regulation?
A: It is difficult to build a modern industrial sector using traditional procedures.
Digital transformation should not be limited to automating the submission of applications. It should
extend to data exchange among authorities, standardization of documents, tracking of licenses,
integration of databases, reduction of repeated requests for the same information, and greater
procedural transparency.
Technology can thereby evolve from a mere administrative tool into an instrument of legislative
and regulatory reform. Genuine digitalization does not simply mean converting paper into a
screen; it means redesigning the procedure itself so that it becomes faster, more transparent, and
more efficient.
THE FUTURE OF INVESTMENT
Q: How will the investment and business landscape in the Middle East change in the
coming years?
A: I believe we are witnessing a genuine reshaping of the investment landscape across the region.
Competition among states will no longer be based solely on market size or operating costs, but
on the overall quality of the investment environment: legislation, regulation, technology, capital,
infrastructure, talent, and the speed of decision-making.
I expect stronger growth in sectors related to technology, artificial intelligence, energy, financial
services, infrastructure, advanced real estate, and logistics, alongside an increase in cross-border
investment among Arab markets themselves.
In my view, the most successful states will be those capable of building an environment that
investors can predict, navigate quickly, and rely upon for effective legal protection.
The region’s future will also depend not only on competition, but on economic and legislative
integration. The easier and clearer the movement of capital and business becomes among Arab
states, the greater the region’s collective ability to attract global investment.
Ultimately, I do not believe the future of investment in the Middle East will be determined solely
by who has the largest market, but by who can provide the most reliable, flexible, and scalable
environment.
This is precisely where law becomes part of a state’s competitive capacity, rather than merely a
tool for regulating it.