
AI and Data Are Pushing Middle East Banks to Redefine the Customer Experience
Artificial intelligence is beginning to change the meaning of customer experience in Middle East banking, as financial institutions move beyond mobile apps and digital self-service toward systems capable of understanding customer behavior, anticipating needs and delivering increasingly personalized financial services.
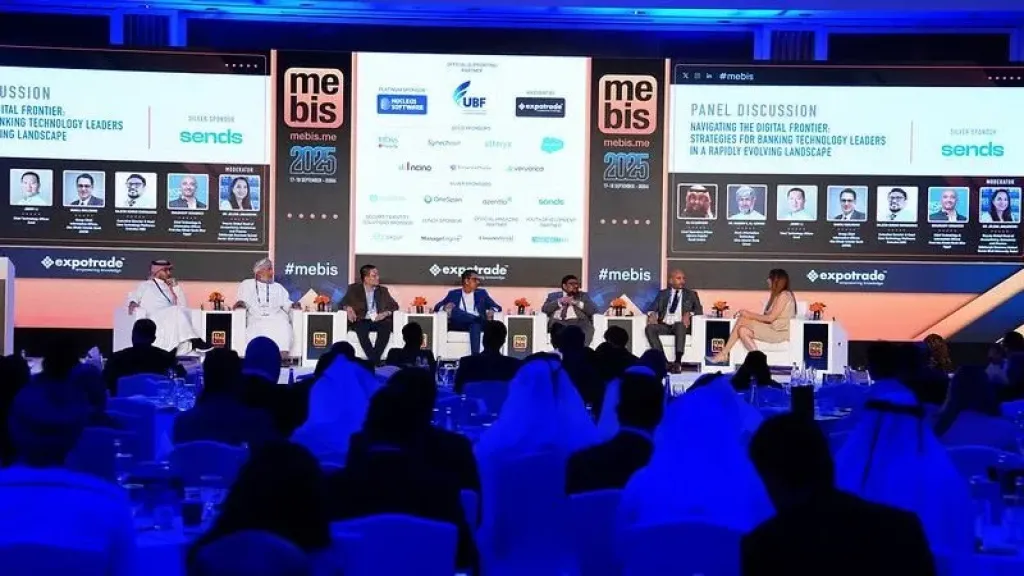
The shift emerged as a central theme at the Middle East Banking Innovation Summit 2026 (MEBIS) in Dubai, where banking executives and technology specialists are examining how AI, data analytics and automation are moving from experimental projects into the operational core of financial institutions.
The change marks a new phase in the region’s banking transformation. For years, the industry focused on digitizing transactions that previously required a branch visit. The next competitive battleground is increasingly about what banks can do with the data generated by those digital interactions.
From digital access to intelligent interaction
Mobile banking has already changed how customers transfer money, pay bills and manage accounts. AI could change what happens before, during and after those transactions.
Banks are exploring how customer data can be analyzed to identify patterns, personalize products and provide relevant services at the right moment rather than presenting every customer with the same offers.
Generative AI adds another layer by allowing customers to interact with banking systems using natural language, while AI-powered assistants can potentially navigate several systems to answer more complex questions.
The emergence of agentic AI could push that model further, with AI agents designed to complete multi-step tasks rather than simply respond to individual prompts.
For banks, this represents a shift from digital self-service toward what could become intelligent financial assistance.
Data becomes the foundation
The technology, however, depends heavily on the quality of the data behind it.
Banks hold enormous volumes of information about transactions, payments and customer interactions, but fragmented databases and legacy systems can make that information difficult to use effectively.
That explains why discussions around data architecture, governance and analytics are increasingly inseparable from the AI conversation.
A sophisticated AI model cannot compensate for inaccurate, incomplete or poorly governed data. As banks deploy AI more widely, the ability to organize and securely connect information across different parts of the institution becomes a competitive capability in its own right.
Personalization comes with a trust challenge
Using more customer data also raises questions that banks cannot treat simply as technology problems.
Customers need to understand how their information is being used, while financial institutions must maintain privacy, cybersecurity and regulatory compliance as AI becomes more deeply embedded in customer interactions.
The challenge becomes even greater when algorithms move beyond recommending products and begin influencing areas such as credit assessment, fraud detection or financial advice.
That means the industry’s move toward personalization must be accompanied by stronger governance and clear boundaries over where automated decisions end and human oversight begins.
The branch-to-app transformation was only the first step
The first generation of digital banking largely replicated traditional banking services on smartphones.
The next generation could be fundamentally different.
Instead of requiring customers to search through menus for the right service, banks are moving toward interfaces that can understand what customers are trying to achieve. Instead of waiting for customers to request assistance, data analytics could help identify needs before they are explicitly expressed.
That transformation could also affect the physical branch.
As routine transactions continue migrating to digital channels, branches can increasingly focus on complex financial decisions and relationship management, while AI handles more repetitive interactions across digital channels.
Customer experience becomes a data competition
The implications extend beyond better chatbots.
As open banking, APIs and embedded finance allow financial products to appear inside third-party platforms, banks risk losing control of the direct customer relationship if their own experiences fail to keep pace.
AI and data therefore become strategic tools for maintaining that relationship.
The banks able to combine trusted customer data, intelligent automation and human expertise could deliver services that feel less like a collection of financial products and more like an ongoing financial relationship.
That is the deeper transformation emerging from MEBIS 2026: the banking industry has largely solved the question of how to put banking services on a screen. The next challenge is making those services understand the customer behind it.